Sari la conținutul principal

Căutare după hashtag

What if the stock market delivers much lower returns over the next decade than investors have become accustomed to?

That’s the scenario retirement savers may need to consider.

Vanguard currently estimates average annual U.S. stock returns of roughly 4.8%–6.8% over the next 10 years, while Fidelity projects about 5.8% annually over 20 years — around 3.2% after inflation.

That’s significantly below the roughly 10% historical average often associated with the S&P 500.

It doesn’t mean investors should abandon equities.

It does mean retirement plans built around optimistic return assumptions may deserve another look.

Higher contributions, realistic retirement timelines, diversification and regular portfolio reviews could become increasingly important if future returns are more modest.

One of the most dangerous assumptions in long-term investing is that the next 20 years must look like the last 20.

Forecasts can be wrong.

But a resilient financial plan shouldn’t depend on everything going right.

#Investing #Retirement #PersonalFinance #StockMarket #FinancialPlanning #Wealth
Imagine din postare
Debt can hold you back from living the life you truly want—especially in retirement.
Don’t let it follow you into your future. Start planning now to pay it down and move toward the financial freedom you deserve.
#debtfree #retirement #suzeorman
12
Building wealth is about consistency, not just how much you earn. Maxing out your Roth IRA can help you take advantage of tax-free growth over time.

Check Out @public's Reserve membership.

#richhabits #retirement #RothIRA #personalfinance https://t.co/9Kgj6gRRgL
7
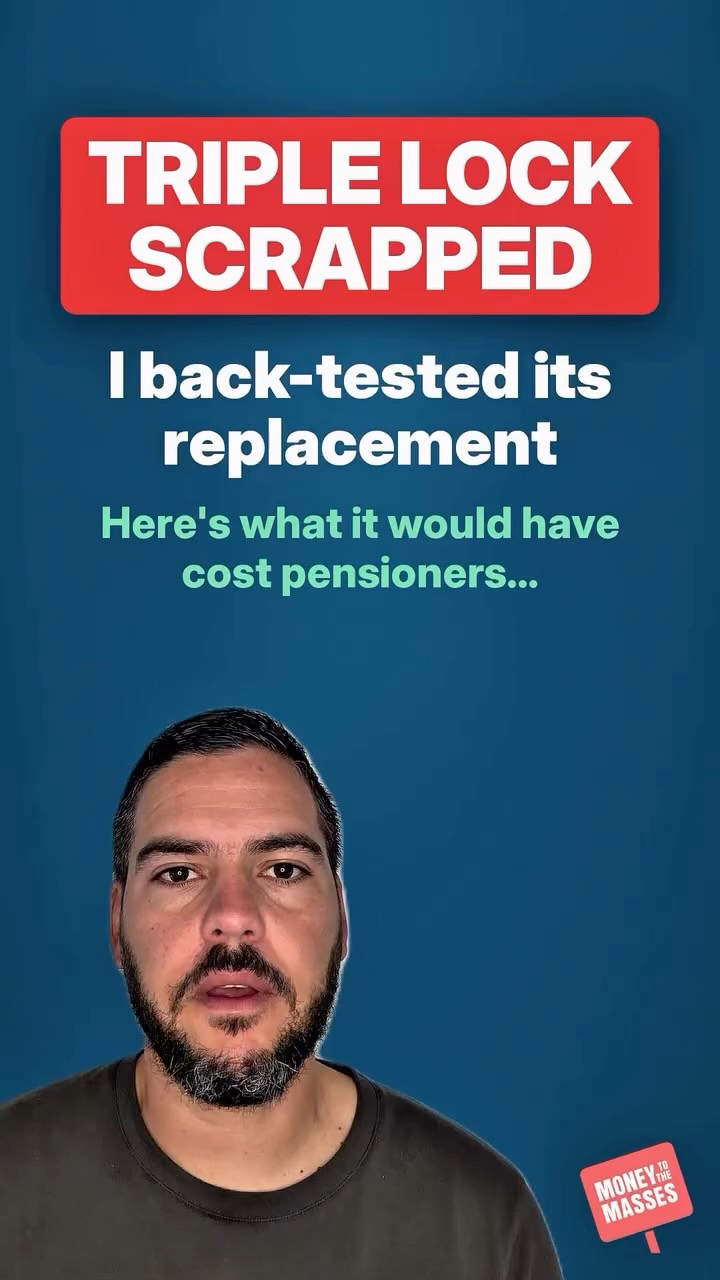
The triple lock is being scrapped. Here’s what its replacement would have meant for pensioners.

Prime Minister Andy Burnham has confirmed that from April 2030 the state pension will rise by the higher of September inflation or 2.5%, plus a promise that it keeps pace with earnings over the long term. The current triple lock (the highest of earnings, inflation or 2.5%) stays in place until then.

I back-tested the replacement on every state pension rise since 2012. Only 6 of the 15 years would have been different, and every one of those would have been lower. Today the full new state pension would be £228.05 a week instead of £241.30, which is about £689 a year less. The full basic state pension would be around £564 a year lower.

Why it’s changing:
💷 The state pension costs around £154bn a year, and the IFS estimates the triple lock has added about £16bn a year since 2010
🧾 Had the replacement been in place since 2011, the Treasury would be saving about £9bn a year today
🏥 The government wants to put the savings towards a National Care Service, estimated to cost around £18bn a year

The big unknown is the earnings promise. Since 2012, inflation plus the 2.5% floor would have beaten wage growth, so the guarantee would never have kicked in. The government also hasn’t said how it will be measured.

What this means for you:
✅ Nothing changes before 2030, and it still has to get through an election first
✅ Get a state pension forecast and check your National Insurance record
✅ Don’t rely on the state pension alone, as the full new state pension is about £12,500 a year
✅ Watch the tax threshold. The personal allowance is frozen at £12,570, so the state pension is heading into taxable territory

Full breakdown explanation and analysis via the LINK IN BIO

Should the triple lock stay or go? Let me know below 👇

#triplelock #pensions #retirement #personalfinance #ukpensions
10
One of the questions I get most about my investing strategy (invest early and often, take advantage of all tax advantaged accounts) is this: “What if I want to retire early and all my money is LOCKED AWAY in retirement accounts?!”⁣‎
⁣‎
That is what I call “a good problem to have”. If your big worry is that you’re going to be SO RICH that you don’t need to work, EXCEPT for fearing a potential 10% early withdrawal penalty on money you take out before you’re 59.5 years old, I think you’re in pretty good shape.‎
‎
That said, there are a LOT of ways to get at that money without the 10% penalty. Namely:‎
⁣‎
1. Brokerage Account: If you really do have enough wealth to retire early, it’s very likely all that money didn’t fit under the relatively low contribution limits for retirement accounts. The excess will be in a brokerage account where you can withdraw any time.⁣‎
2. Investment Real Estate: Similarly, wealthy people generally end up owning properties. The income can support you at any time as it’s not in a retirement account.⁣‎
3. Roth IRA principal: When you contribute to a Roth IRA, you can always take out what you put in at any time with no tax or penalty.⁣‎
4. Roth Conversion Ladder: Any money contributed to traditional accounts can be converted to Roth and then withdrawn after 5 years.⁣‎
5. Rule 72(t): A law designed for early retirees. Basically, you can set up scheduled withdrawals of a reasonable amount without any penalties.⁣‎
6. Rule of 55: If you happen to quit between 55 and 59.5, you can access everything penalty free.⁣‎
⁣‎
The above list gives MORE than enough ways to access plenty of that money when you need it (and you’ll want the rest to stay in tax advantaged accounts for years 59.5 to 100+ anyway!)⁣. So don’t fear your money being locked away. Be aggressive about maximizing every tax advantage the IRS will afford you.‎
⁣‎
As always, reminding you to build wealth by following the two PFC rules: 1.) Live below your means and 2.) Invest early and often.⁣‎
⁣‎
– Jeremy⁣‎

#investing #retirement #earlyretirement #FIRE #financialindependence #rothIRA #401k
883