
Diseara de la 19:00, pe youtube, premiera, link in comment.
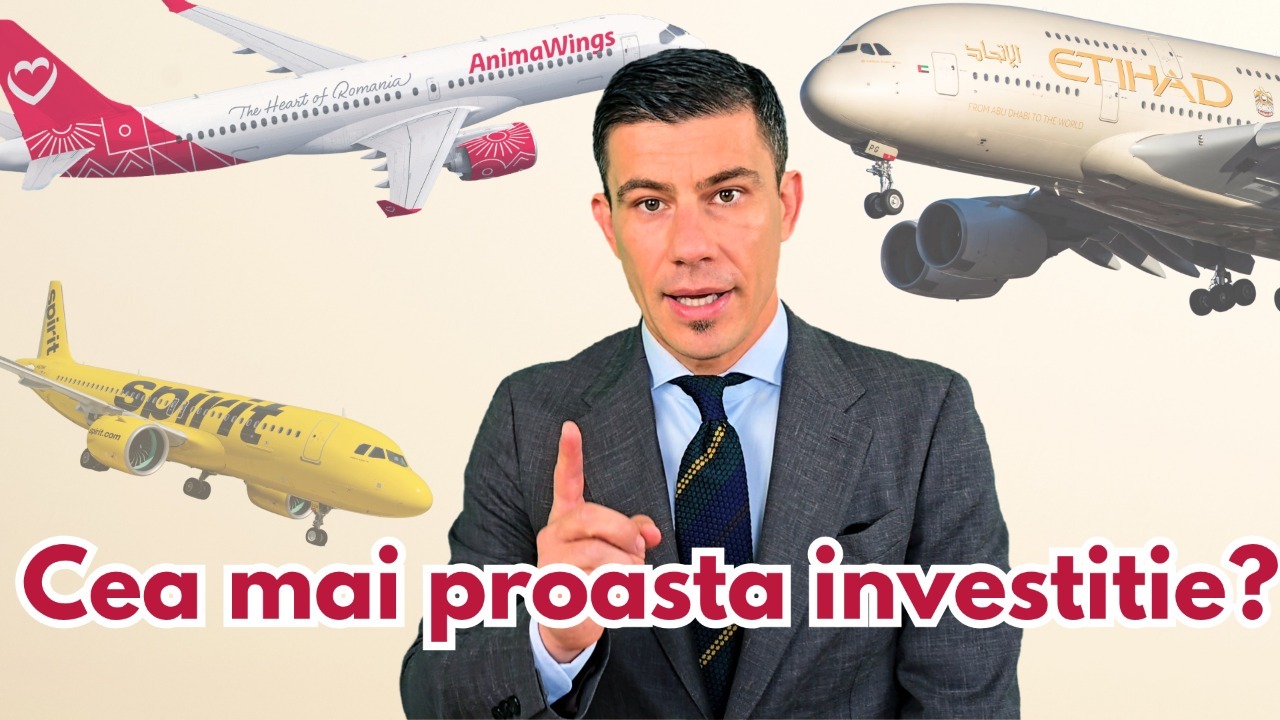
Warren Buffett a spus că daca vrei să cumperi o companie, sune mai întâi la o linie de ajutor pentru aeroholici. Animawings tocmai ne-a arătat de ce, cu o insolvență venita după ani în care a confirmat toate trope-urile despre cat de grea e aceasta industrie.
Analizam bilanțurile Animawings, evolutia capitalulului propriu care a ajuns de la 6,6 milioane de lei la minus 107,7 milioane într-un singur an si comparam cu Etihad Airways, care are exact același model (profituri mici, pierderi mari) și care există și azi doar pentru că are în spate un robinet cu bani aproape fără sfârșit.
Ce discutăm în episod:
±De ce afacerea cu avioane are profituri mici în anii buni și pierderi imense în anii răi
± Cazurile AnimaWings, Etihad si Spirit Airline
± Cât a câștigat, de fapt, industria aeriană mondială în istoria ei, și ce spun IATA, McKinsey și studiile academice
± Sutele de companii aeriene dispărute între 2000 și 2025
± Discursul lui Warren Buffett de la Sun Valley: diferența dintre o industrie care schimbă lumea și una care face bani pentru investitori
± Spirit Airlines: cronologia insolvenței versus procesul DOJ, cu efectele asupra clienților, acționarilor și obligatarilor
Mă întreb dacă voi ați pățit ceva asemănător, adică ați cumpărat acțiuni la o companie dintr-o industrie care vă plăcea enorm și care s-a dovedit un hobby scump, așa că scrieți-mi în comentarii povestea voastră și ce ați învățat din ea.
#investitii #bursa #educatiefinanciara #libertatefinanciara #warrenbuffett #actiuni #companiiaeriene #animawings #spiritairlines #finantepersonale
#investing #stockmarket #valueinvesting #warrenbuffett #berkshirehathaway #airlines #airlineindustry #mergerarbitrage #etihad #personalfinance
1
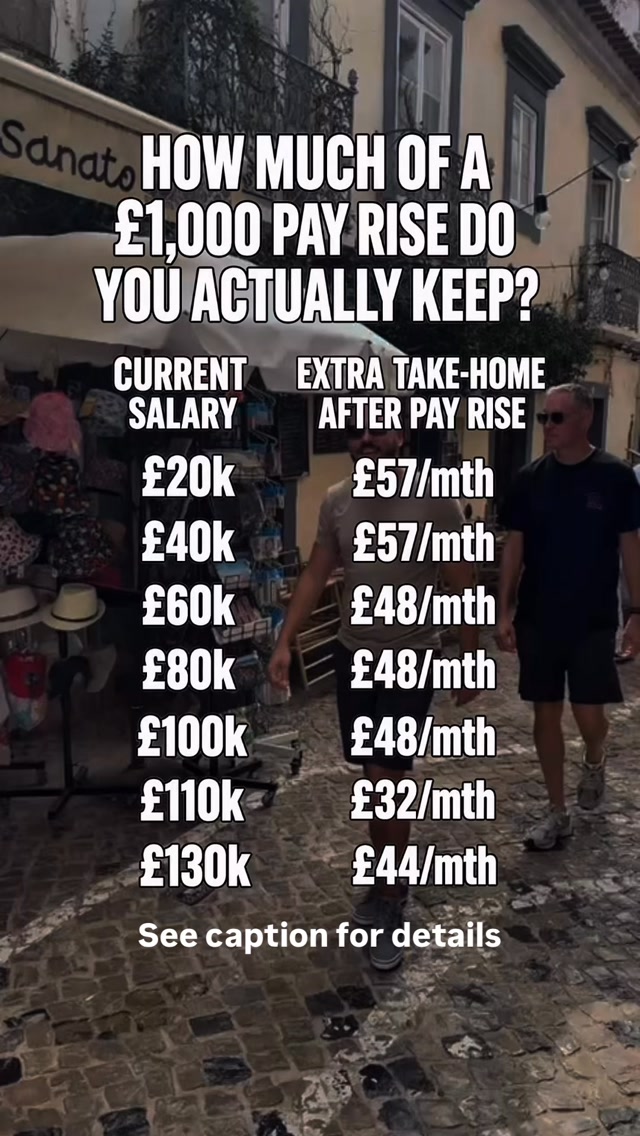
When negotiating a pay rise you need to know how much of a £1,000 pay rise do you actually keep?
The answer depends on what you already earn.
This table shows the extra monthly take-home pay from a £1,000 increase in annual gross salary.
At £20k or £40k, you keep around £57 a month.
At £60k, £80k and £100k, it’s around £48 a month.
At £110k, it falls to roughly £32 a month because of the Personal Allowance taper, which can create an effective 60% income-tax rate on part of your income.
By £130k, it rises again to around £44 a month because the Personal Allowance has already been lost and the marginal income-tax rate is 45%, plus employee National Insurance.
The figures assume:
* you’re employed and paid through PAYE
* you live in England, Wales or Northern Ireland
* standard tax code
* standard employee National Insurance
* minimum auto-enrolment pension contributions using relief at source
* no student loan, salary sacrifice or other deductions
Under relief at source, the minimum employee-side auto-enrolment contribution is typically 5% of qualifying earnings, but only 4% comes from your take-home pay, with basic-rate tax relief making up the other 1%. Employer minimum contributions are generally 3%. Qualifying earnings for 2026/27 run from £6,240 to £50,270.
So the point is simple:
A £1,000 pay rise doesn’t mean £1,000 more in your pocket. And the amount you keep can vary dramatically depending on where you sit in the tax system.
As a general rule of thumb, multiply the figures by five for a £5,000 pay rise, or by ten for a £10,000 rise. However, this won’t be exact if your pay rise crosses key tax thresholds.
#personalfinance #costofliving #ukmoney #personalfinanceuk #moneytips
7
Most of what people worry about with money doesn’t move the needle at all. Headlines about the interest rates, inflation, and market crashes are designed to scare you, not help you build wealth. Even though I love to talk about the fine tuning, we can’t lose sight of what makes the biggest impact.
Instead of running through the desert and worrying about whether the tectonic plates are shifting, focus on running faster and running further if that’s your goal.
It’s the same with money. The hacks are fun, but they’re a distraction from the two things that actually matter: earning more and spending less. The gap between those two numbers is the entire ballgame. A mediocre investor putting away $1,000 a month will beat an optimal investor saving $100 a month, every time.
“I don’t understand dividend reinvestment, so I’m gonna spend every dollar I earn” keeps you broke. “I don’t understand investing, so I’m gonna work on saving while I learn more” is how broke people become millionaires.
Focus on the big stuff. Keep learning along the way. Become a millionaire. Retire early. That’s the real wealth-building hack.
As always, reminding you to build wealth by following the two PFC rules: 1.) Live below your means and 2.) Invest early and often.
-Jeremy & Jenn
#personalfinance #investing #wealthbuilding #financialfreedom #moneytips #learntoinvest #retireearly #financialindependence #savemoney #investearly
16
Learn from my mistakes! 💖
👉 Save this post
👇 Comment ‘BUDGET’ for the exact tool I use to track my finances
Every year you put off learning about money is a year longer you will have to work 👀
Let’s get you working smarter not harder. ✅
👉 DM me INVEST to apply for 1:1 coaching
#personalfinance
👉 Save this post
👇 Comment ‘BUDGET’ for the exact tool I use to track my finances
Every year you put off learning about money is a year longer you will have to work 👀
Let’s get you working smarter not harder. ✅
👉 DM me INVEST to apply for 1:1 coaching
#personalfinance
7
Want to know which ETFs I personally like for long-term investing? 📈
There are plenty of ETFs out there, but you don’t need to own dozens of them. The key is understanding what you’re investing in, how diversified it is, and why it fits your goals.
I broke down 5 ETFs covering U.S. stocks, technology, dividends, and international markets.
💬 Comment your favorite ETF + follow me if you’re trying to catch up with investing!
— Steve
Follow @calltoleap
Follow @calltoleap for investing videos
Follow me @calltoleap to start your journey toward financial freedom!
#ETFs #InvestingForBeginners #Investing101 #IndexFunds #LongTermInvesting #WealthBuilding #PersonalFinance #InvestingTips #FinancialFreedom #CallToLeap
1.6K