Most of what people worry about with money doesn’t move the needle at all. Headlines about the interest rates, inflation, and market crashes are designed to scare you, not help you build wealth. Even though I love to talk about the fine tuning, we can’t lose sight of what makes the biggest impact.
Instead of running through the desert and worrying about whether the tectonic plates are shifting, focus on running faster and running further if that’s your goal.
It’s the same with money. The hacks are fun, but they’re a distraction from the two things that actually matter: earning more and spending less. The gap between those two numbers is the entire ballgame. A mediocre investor putting away $1,000 a month will beat an optimal investor saving $100 a month, every time.
“I don’t understand dividend reinvestment, so I’m gonna spend every dollar I earn” keeps you broke. “I don’t understand investing, so I’m gonna work on saving while I learn more” is how broke people become millionaires.
Focus on the big stuff. Keep learning along the way. Become a millionaire. Retire early. That’s the real wealth-building hack.
As always, reminding you to build wealth by following the two PFC rules: 1.) Live below your means and 2.) Invest early and often.
-Jeremy & Jenn
#personalfinance #investing #wealthbuilding #financialfreedom #moneytips #learntoinvest #retireearly #financialindependence #savemoney #investearly
16
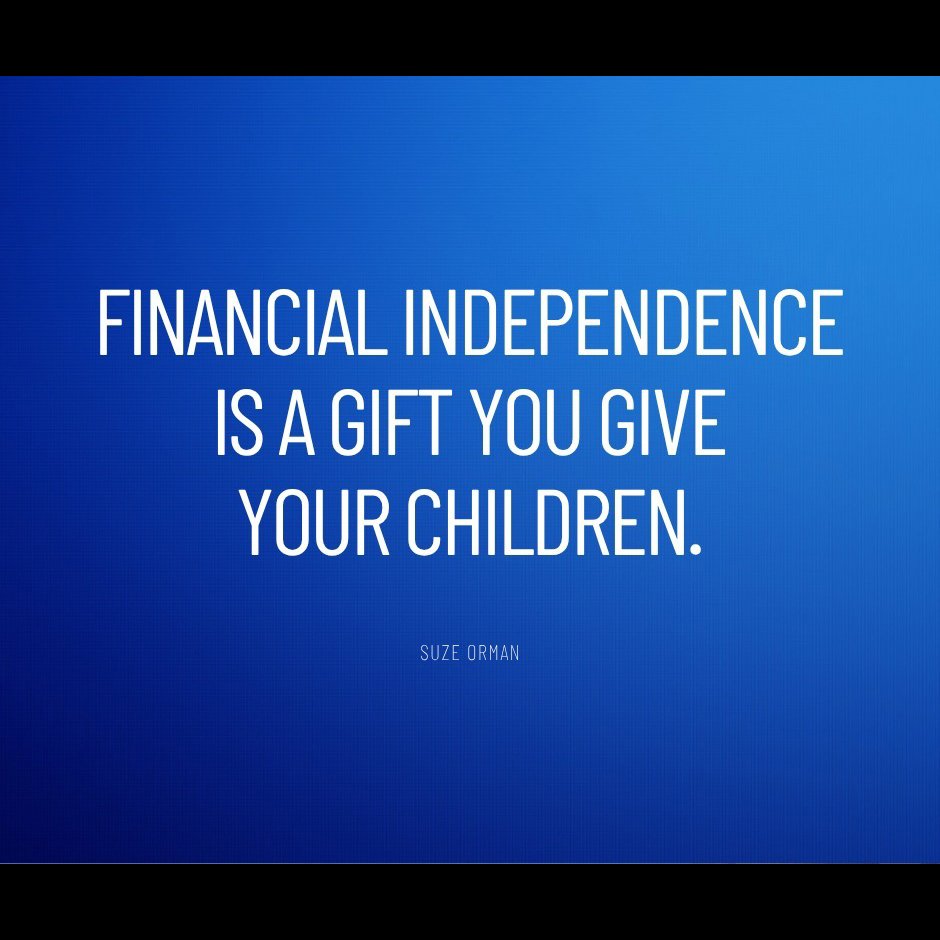
Parents, loving your adult children doesn't mean you have to keep paying their bills.
One of the most important things you can teach your children is how to take financial responsibility for themselves.
Health insurance is a perfect example. Yes, you can keep your adult children on your health insurance until they're 26. But if they're working and have access to benefits through their employer, it's time to sit down together and compare their options.
If their employer's plan offers comparable coverage at a reasonable cost, it may be time for them to take on that responsibility.
And if you can afford to help them make the transition, I have no problem with that. But don't continue paying out of guilt or habit.
Remember, your job as a parent isn't to carry your children financially forever. It's to help them become strong enough to stand on their own.
#financialindependence #financialliteracy #moneyandfamily #parentingadultchildren #financialresponsibility #moneymindset #personalfinance #financialwellness #suzeorman
69
I’m a simple girl. Give me a good rate, a little attention, zero hidden fees, and I might let you buy me dinner.💋
Snacks count as a recurring contribution.
Comment PLAYBOOK for my free Money Era Playbook. A gift from me to you 🎁
-Leandra
.
.
.
#personalfinance #financialfreedom #financialindependence #stockmarketinvesting #passiveincome
Snacks count as a recurring contribution.
Comment PLAYBOOK for my free Money Era Playbook. A gift from me to you 🎁
-Leandra
.
.
.
#personalfinance #financialfreedom #financialindependence #stockmarketinvesting #passiveincome
2.1K
One of the questions I get most about my investing strategy (invest early and often, take advantage of all tax advantaged accounts) is this: “What if I want to retire early and all my money is LOCKED AWAY in retirement accounts?!”
That is what I call “a good problem to have”. If your big worry is that you’re going to be SO RICH that you don’t need to work, EXCEPT for fearing a potential 10% early withdrawal penalty on money you take out before you’re 59.5 years old, I think you’re in pretty good shape.
That said, there are a LOT of ways to get at that money without the 10% penalty. Namely:
1. Brokerage Account: If you really do have enough wealth to retire early, it’s very likely all that money didn’t fit under the relatively low contribution limits for retirement accounts. The excess will be in a brokerage account where you can withdraw any time.
2. Investment Real Estate: Similarly, wealthy people generally end up owning properties. The income can support you at any time as it’s not in a retirement account.
3. Roth IRA principal: When you contribute to a Roth IRA, you can always take out what you put in at any time with no tax or penalty.
4. Roth Conversion Ladder: Any money contributed to traditional accounts can be converted to Roth and then withdrawn after 5 years.
5. Rule 72(t): A law designed for early retirees. Basically, you can set up scheduled withdrawals of a reasonable amount without any penalties.
6. Rule of 55: If you happen to quit between 55 and 59.5, you can access everything penalty free.
The above list gives MORE than enough ways to access plenty of that money when you need it (and you’ll want the rest to stay in tax advantaged accounts for years 59.5 to 100+ anyway!). So don’t fear your money being locked away. Be aggressive about maximizing every tax advantage the IRS will afford you.
As always, reminding you to build wealth by following the two PFC rules: 1.) Live below your means and 2.) Invest early and often.
– Jeremy
#investing #retirement #earlyretirement #FIRE #financialindependence #rothIRA #401k
883

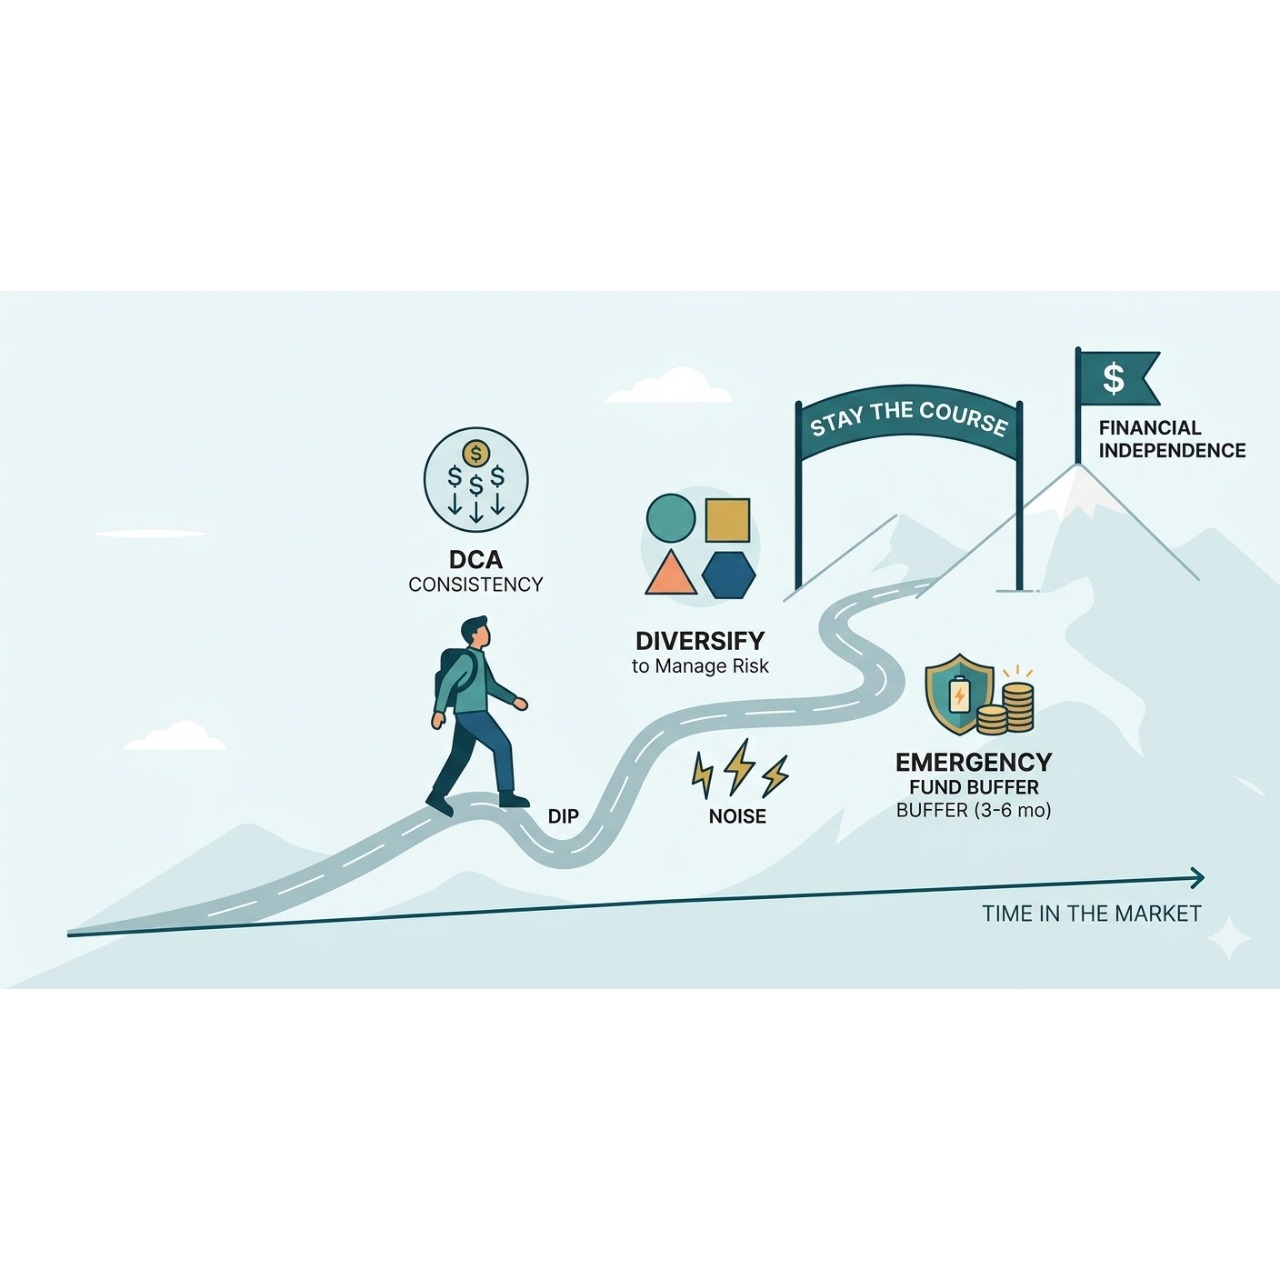
Investing in 2026 is a test of patience, not prediction. 📉 The noise is loud, but the principles remain simple:
Keep DCA (Dollar-Cost Averaging) consistent.
Diversify to manage risk, not just chase returns.
Keep an emergency fund so you aren’t forced to sell during dips.
Time in the market beats timing the market. Every. Single. Time. ⏳🚀
#Investing #FinancialIndependence #WealthBuilding #DCA
Keep DCA (Dollar-Cost Averaging) consistent.
Diversify to manage risk, not just chase returns.
Keep an emergency fund so you aren’t forced to sell during dips.
Time in the market beats timing the market. Every. Single. Time. ⏳🚀
#Investing #FinancialIndependence #WealthBuilding #DCA
2