Andy Constan says rising bond yields are just markets finally catching up to a growth boom driven by AI and the OBBB
You have to look at what’s happened in the bond market. And I put it in context of, man, thanks for finally showing up at the party. We’ve had a meaningful growth impulse for multiple years now, driven by AI capital and capex, which had been going on since 2023, when ChatGPT first was released. It really accelerated last summer, not this summer, the summer before last, with the OBBB, where capex was tax-advantaged by the budget. And so we saw that massive acceleration in growth. The consumer has remained strong, because asset markets have remained robust. And so that combination of things has created an above-trend growth impulse, inflation above target, and, yeah, I mean, catch up bond market. And finally, it did. I don’t know why, perhaps it’s Warsh leaning hawkish and then ultimately hiking. But really, as far as I can tell, the only thing that really has happened in the bond market is that the long end globally has caught up to the idea that we’re in the midst of a growth boom.
#Bonds #Macro
2
Andy Constan says Bessent has been gaslighting markets, his real goal with $128 billion in buybacks was to suppress long-term rates and run the economy hot
On August 19, they decided to increase the Treasury buyback by $128 billion, financing it with no change in any of the coupon issuance, so, by definition, financing it with T-bills. While we’ve been gaslighted by Bessent, sometimes he’s actually revealed his true self. His goal was to suppress long-term interest rates. Full stop. And so the question becomes, why? Why has Bessent decided that, with the economy growing gangbusters, with inflation above target, that it’s time to step in and suppress long-term interest rates? The answer is quite simple. Run it hot. And so that’s the status quo as of today.
#Bessent #Macro
6
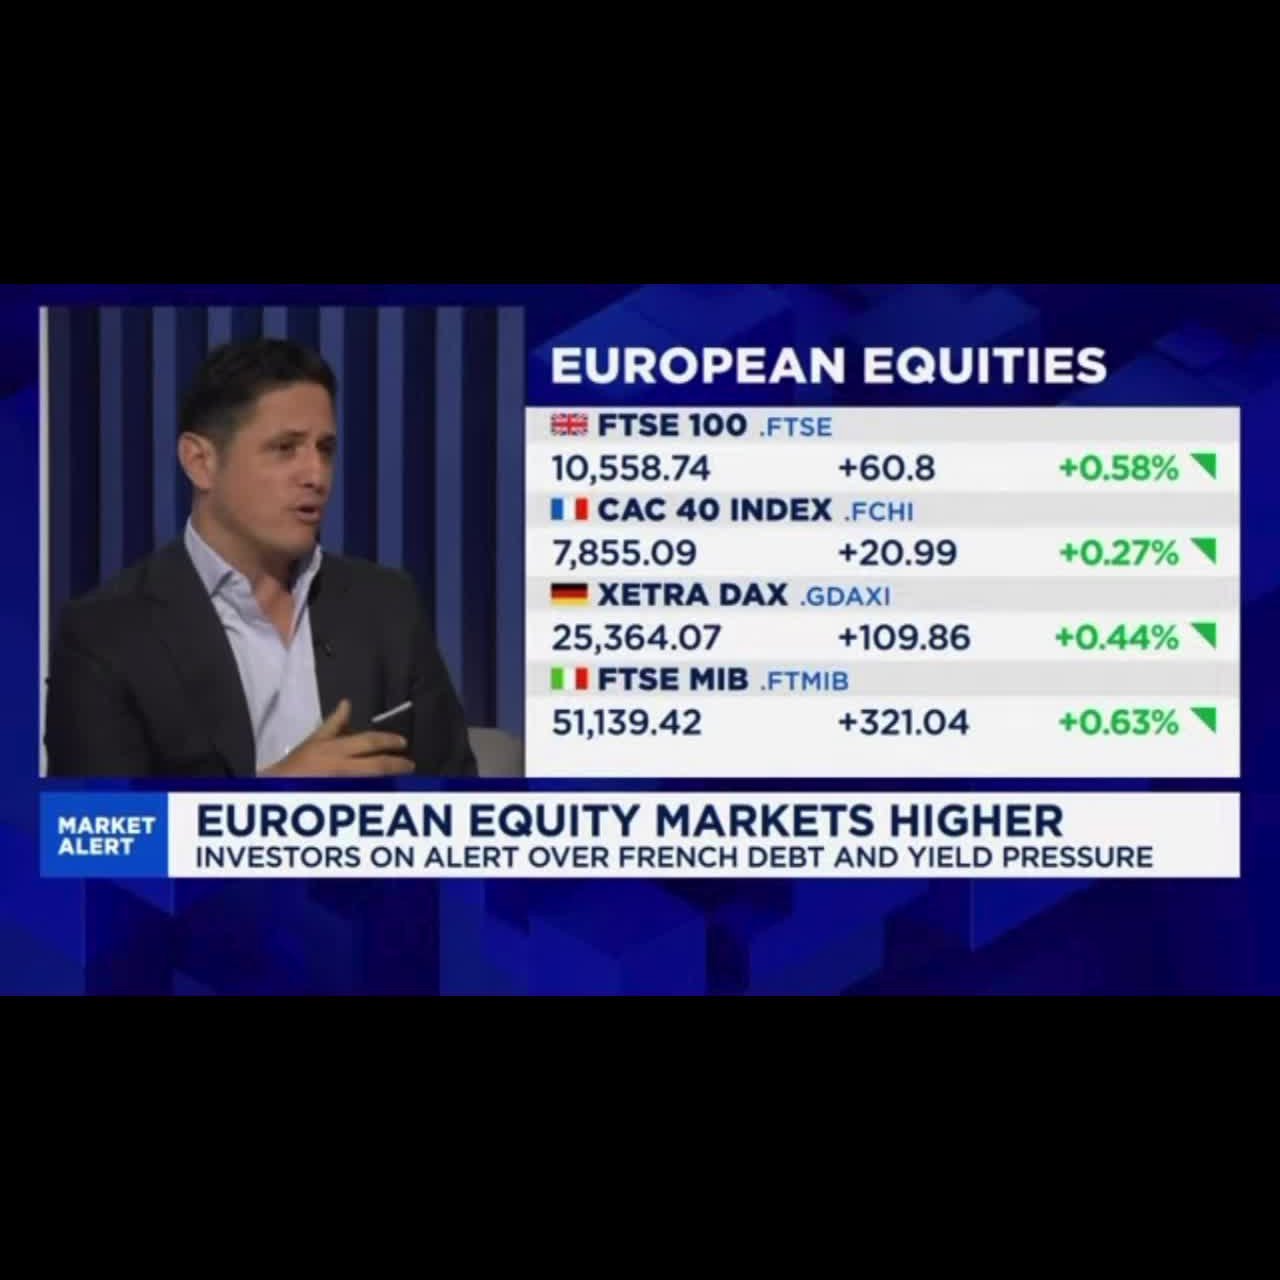
Today, at European markets open, I joined dear friends Steve Sedgwick, Karen Tso and Ben Boulos at CNBC SquawkBox Europe to discuss global markets.
A striking disconnect is opening up across markets.
Bond markets are increasingly focused on fiscal credibility, sovereign debt and the structural cost of capital. Equity markets, by contrast, still seem heavily conditioned to celebrate any softer data as a signal that central banks may become less hawkish. That divergence cannot persist indefinitely.
Europe is a good example. The issue is not whether France is “the next Greece.” The more important question is why markets were willing to give highly indebted developed economies such a long free pass in the first place.
For years, abundant liquidity masked weak fiscal discipline. That era is ending, and the next phase of markets may be shaped less by centralbank liquidity and much more by fiscal discipline, sovereign risk and the real cost of capital.
#CNBC #Markets #FixedIncome #Europe #Macro #TantoCapitalPartners
68

Precious metals are back in the spotlight — but the message from the market is mixed.
Gold and silver pulled back after a strong four-day rally, as traders locked in profits even though softer U.S. jobs data has eased some fears of further Fed rate hikes. Gold remains supported by macro uncertainty, central-bank demand, and expectations that rates may eventually move lower, but near-term volatility is still very much in play.
JPMorgan’s latest outlook reportedly sees gold rising toward $4,300/oz in Q3 and $4,500/oz in Q4, while warning that upside could be limited if inflation data forces the Fed back into a more hawkish stance.
Silver continues to trade with higher beta: stronger upside during risk-on commodity rallies, but sharper pullbacks when sentiment turns. Platinum and palladium are also drawing attention as investors reassess industrial demand, supply risks, and relative value across the metals complex.
Key takeaway: precious metals are no longer just a “safe haven” story. They are increasingly a macro trade — tied to real rates, the dollar, central-bank policy, geopolitical risk, and investor positioning.
For finance professionals and investors, the question is not simply “gold or silver?” It is: how much volatility are you prepared to own in the pursuit of portfolio protection and commodity upside?
#PreciousMetals #Gold #Silver #Commodities #Finance #Investing #Macro #Markets
2
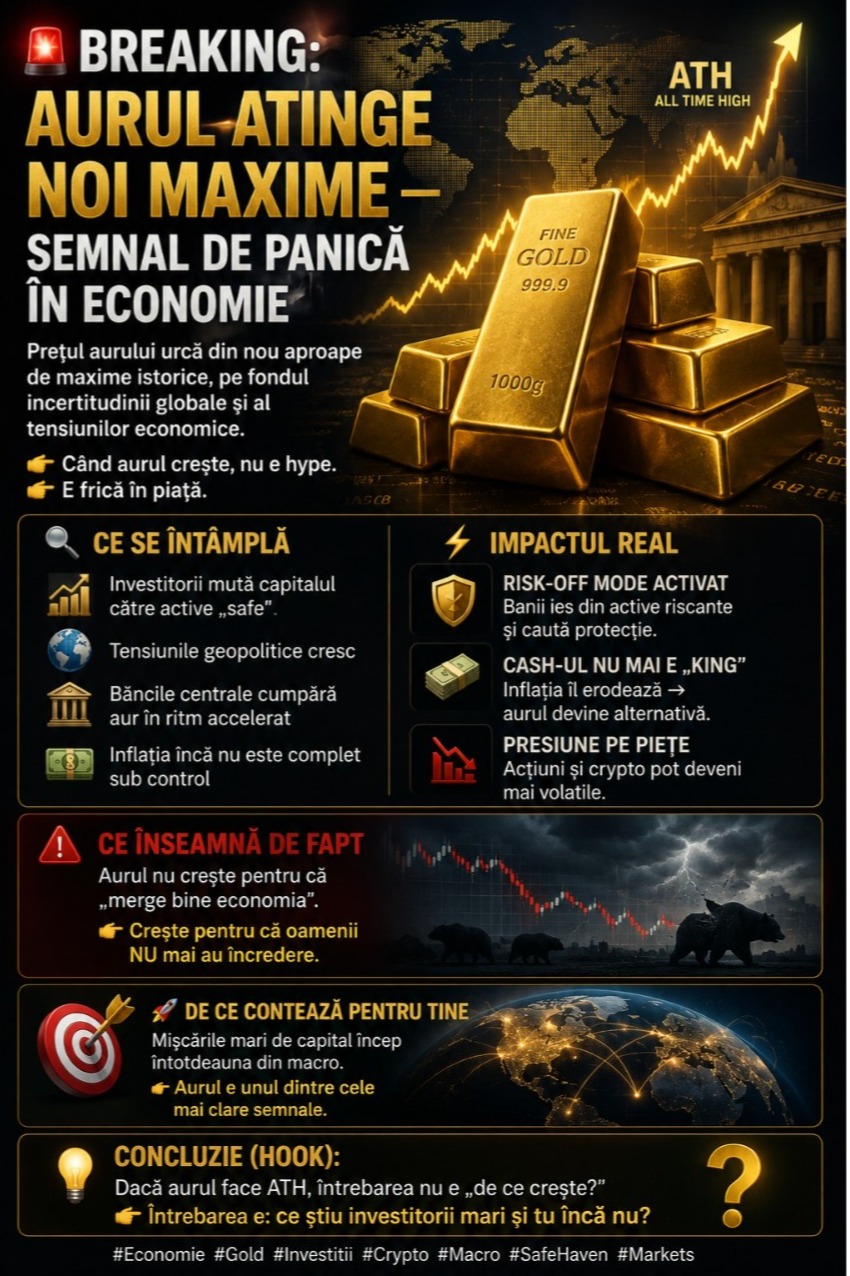
🚨 BREAKING: Aurul atinge noi maxime — semnal de panică în economie
Prețul aurului urcă din nou aproape de maxime istorice, pe fondul incertitudinii globale și al tensiunilor economice.
👉 Când aurul crește, nu e hype.
👉 E frică în piață.
🔎 Ce se întâmplă
📈 Investitorii mută capitalul către active „safe”
🌍 Tensiunile geopolitice cresc
🏦 Băncile centrale cumpără aur în ritm accelerat
💸 Inflația încă nu este complet sub control
⚡ Impactul real
📊 Risk-off mode activat
Banii ies din active riscante și caută protecție.
💰 Cash-ul nu mai e „king”
Inflația îl erodează → aurul devine alternativă.
📉 Presiune pe piețe
Acțiuni și crypto pot deveni mai volatile.
💥 Ce înseamnă de fapt
Aurul nu crește pentru că „merge bine economia”.
👉 Crește pentru că oamenii NU mai au încredere.
🚀 De ce contează pentru tine
Mișcările mari de capital încep întotdeauna din macro.
👉 Aurul e unul dintre cele mai clare semnale.
💡 Concluzie (hook):
Dacă aurul face ATH, întrebarea nu e „de ce crește?”
👉 Întrebarea e: ce știu investitorii mari și tu încă nu?
#Economie #Gold #Investitii #Crypto #Macro #SafeHaven #Markets
2