When negotiating a pay rise you need to know how much of a £1,000 pay rise do you actually keep?
The answer depends on what you already earn.
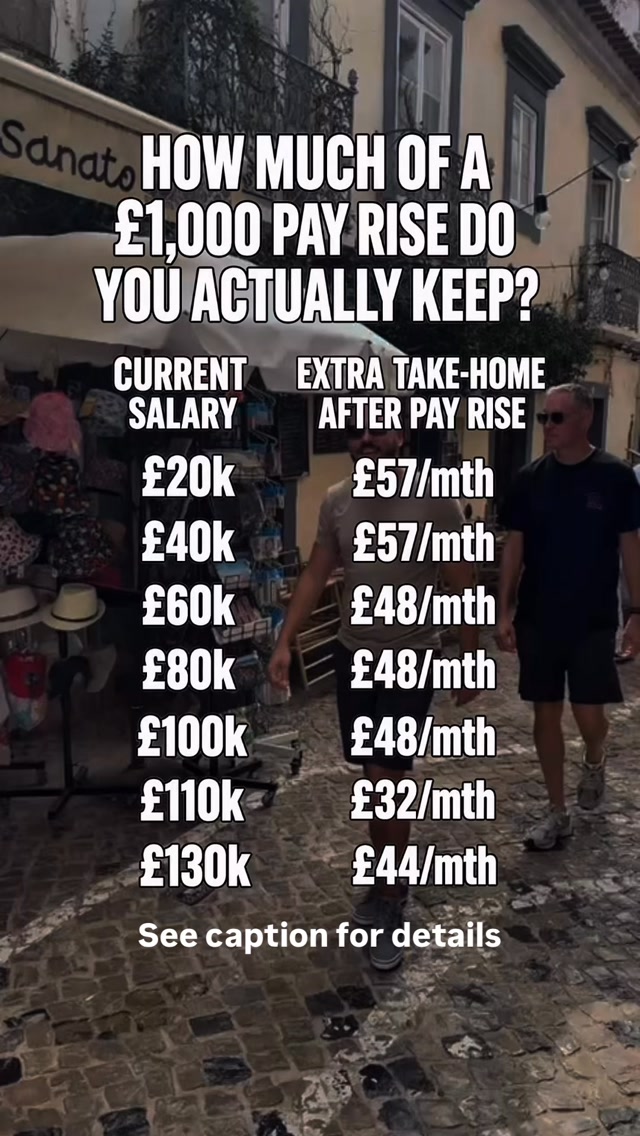
This table shows the extra monthly take-home pay from a £1,000 increase in annual gross salary.
At £20k or £40k, you keep around £57 a month.
At £60k, £80k and £100k, it’s around £48 a month.
At £110k, it falls to roughly £32 a month because of the Personal Allowance taper, which can create an effective 60% income-tax rate on part of your income.
By £130k, it rises again to around £44 a month because the Personal Allowance has already been lost and the marginal income-tax rate is 45%, plus employee National Insurance.
The figures assume:
* you’re employed and paid through PAYE
* you live in England, Wales or Northern Ireland
* standard tax code
* standard employee National Insurance
* minimum auto-enrolment pension contributions using relief at source
* no student loan, salary sacrifice or other deductions
Under relief at source, the minimum employee-side auto-enrolment contribution is typically 5% of qualifying earnings, but only 4% comes from your take-home pay, with basic-rate tax relief making up the other 1%. Employer minimum contributions are generally 3%. Qualifying earnings for 2026/27 run from £6,240 to £50,270.
So the point is simple:
A £1,000 pay rise doesn’t mean £1,000 more in your pocket. And the amount you keep can vary dramatically depending on where you sit in the tax system.
As a general rule of thumb, multiply the figures by five for a £5,000 pay rise, or by ten for a £10,000 rise. However, this won’t be exact if your pay rise crosses key tax thresholds.
#personalfinance #costofliving #ukmoney #personalfinanceuk #moneytips
7
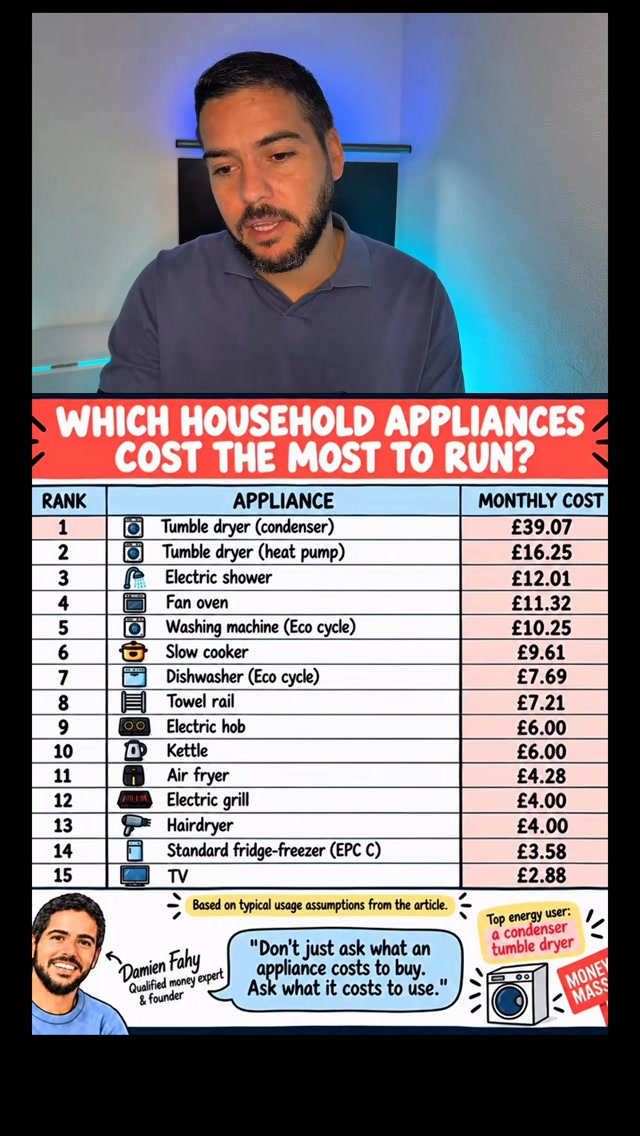
The most expensive thing in your house to run is almost certainly your tumble dryer 😬
Here is what each appliance costs per month, if you use it every day:
👕 Tumble dryer, condenser, one full load a day: £39.07
♻️ Tumble dryer, heat pump, one full load a day: £16.25
🚿 Electric shower, 10 mins a day: £12.01
🔥 Fan oven, 1 hour a day: £11.32
🧺 Washing machine, eco, one full load a day: £10.25
🍲 Slow cooker, 6 hours a day: £9.61
🍽️ Dishwasher, eco, one cycle a day: £7.69
🛁 Towel rail, 2 hours a day: £7.21
🍳 Electric hob, 30 mins a day: £6.00
☕ Kettle, 15 mins a day: £6.00
🍟 Air fryer, 30 mins a day: £4.28
🥩 Electric grill, 20 mins a day: £4.00
💇 Hairdryer, 15 mins a day: £4.00
🧊 Fridge freezer (EPC C), on 24 hours: £3.58
📺 TV, 3 hours a day: £2.88
Two things stand out. A heat pump tumble dryer does the same job for less than half the cost of a condenser one. And the air fryer costs about a third of the fan oven to run, which settles that argument.
The assumptions, so you can judge for yourself:
📌 Electricity at 26.32p per kWh, the Ofgem price cap from 1 October 2026
📌 Standing charges are not included, since you pay those whatever you use
📌 Each appliance is costed on daily use, for example 10 minutes in the shower, an hour with the oven on, 6 hours in the slow cooker, 30 minutes for the hob and the air fryer, 15 minutes for the kettle, and one full cycle a day for the washing machine, dishwasher and tumble dryer
📌 Based on average wattage, so your own appliance could be more or less efficient
Use less than that and your cost drops in proportion. Use more and it climbs.
The bigger point: when you buy an appliance, the price on the label is only half the cost. A cheap tumble dryer that costs £39 a month to run is not cheap. Check the energy rating before you buy, because once you own it, it could cost you a small fortune.
Full table for every appliance in the home is on Money to the Masses, link in bio 🔗
Which one surprised you? 👇
#energybills #costofliving #ukmoney #personalfinanceuk #moneytips
1.2K
What could overpaying an extra £100 a month do to your mortgage?
Potentially, quite a lot.
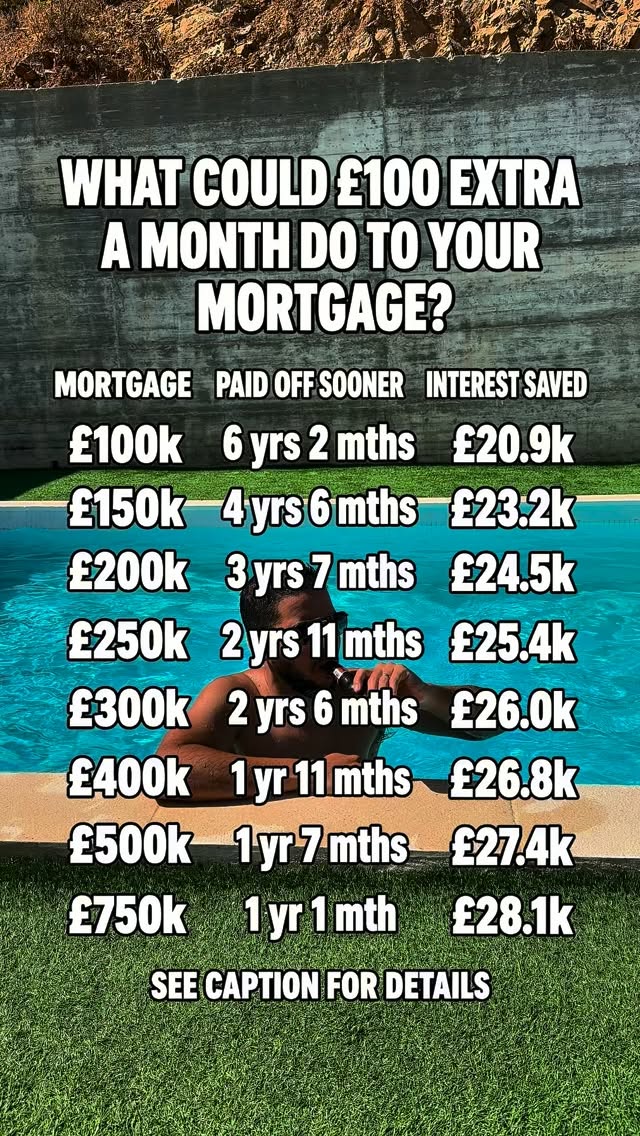
This table shows how much sooner you could repay your mortgage, and roughly how much interest you could save, if you overpaid by £100 every month.
For example:
* £100k mortgage → paid off about 6 years 2 months sooner, saving around £20,900 in interest
* £200k mortgage → about 3 years 7 months sooner, saving around £24,500
* £500k mortgage → about 1 year 7 months sooner, saving around £27,400
The figures assume:
* a repayment mortgage
* 25 years remaining
* an interest rate of 5%
* the rate stays at 5% for the whole period
* you start overpaying immediately and continue every month
* no overpayment charges
Your actual saving will depend on your mortgage rate, remaining term and whether your lender limits penalty-free overpayments.
And remember, overpaying your mortgage is not automatically the best use of spare cash. Depending on your rate and circumstances, saving or investing could potentially give you a better return.
But if your priority is to clear your mortgage sooner and reduce the amount of interest you pay, even an extra £100 a month can make a meaningful difference.
For more info on overpaying your mortgage including the pros and cons click the LINK IN BIO
#mortgage #ukmoney #personalfinance #property #moneytips
24
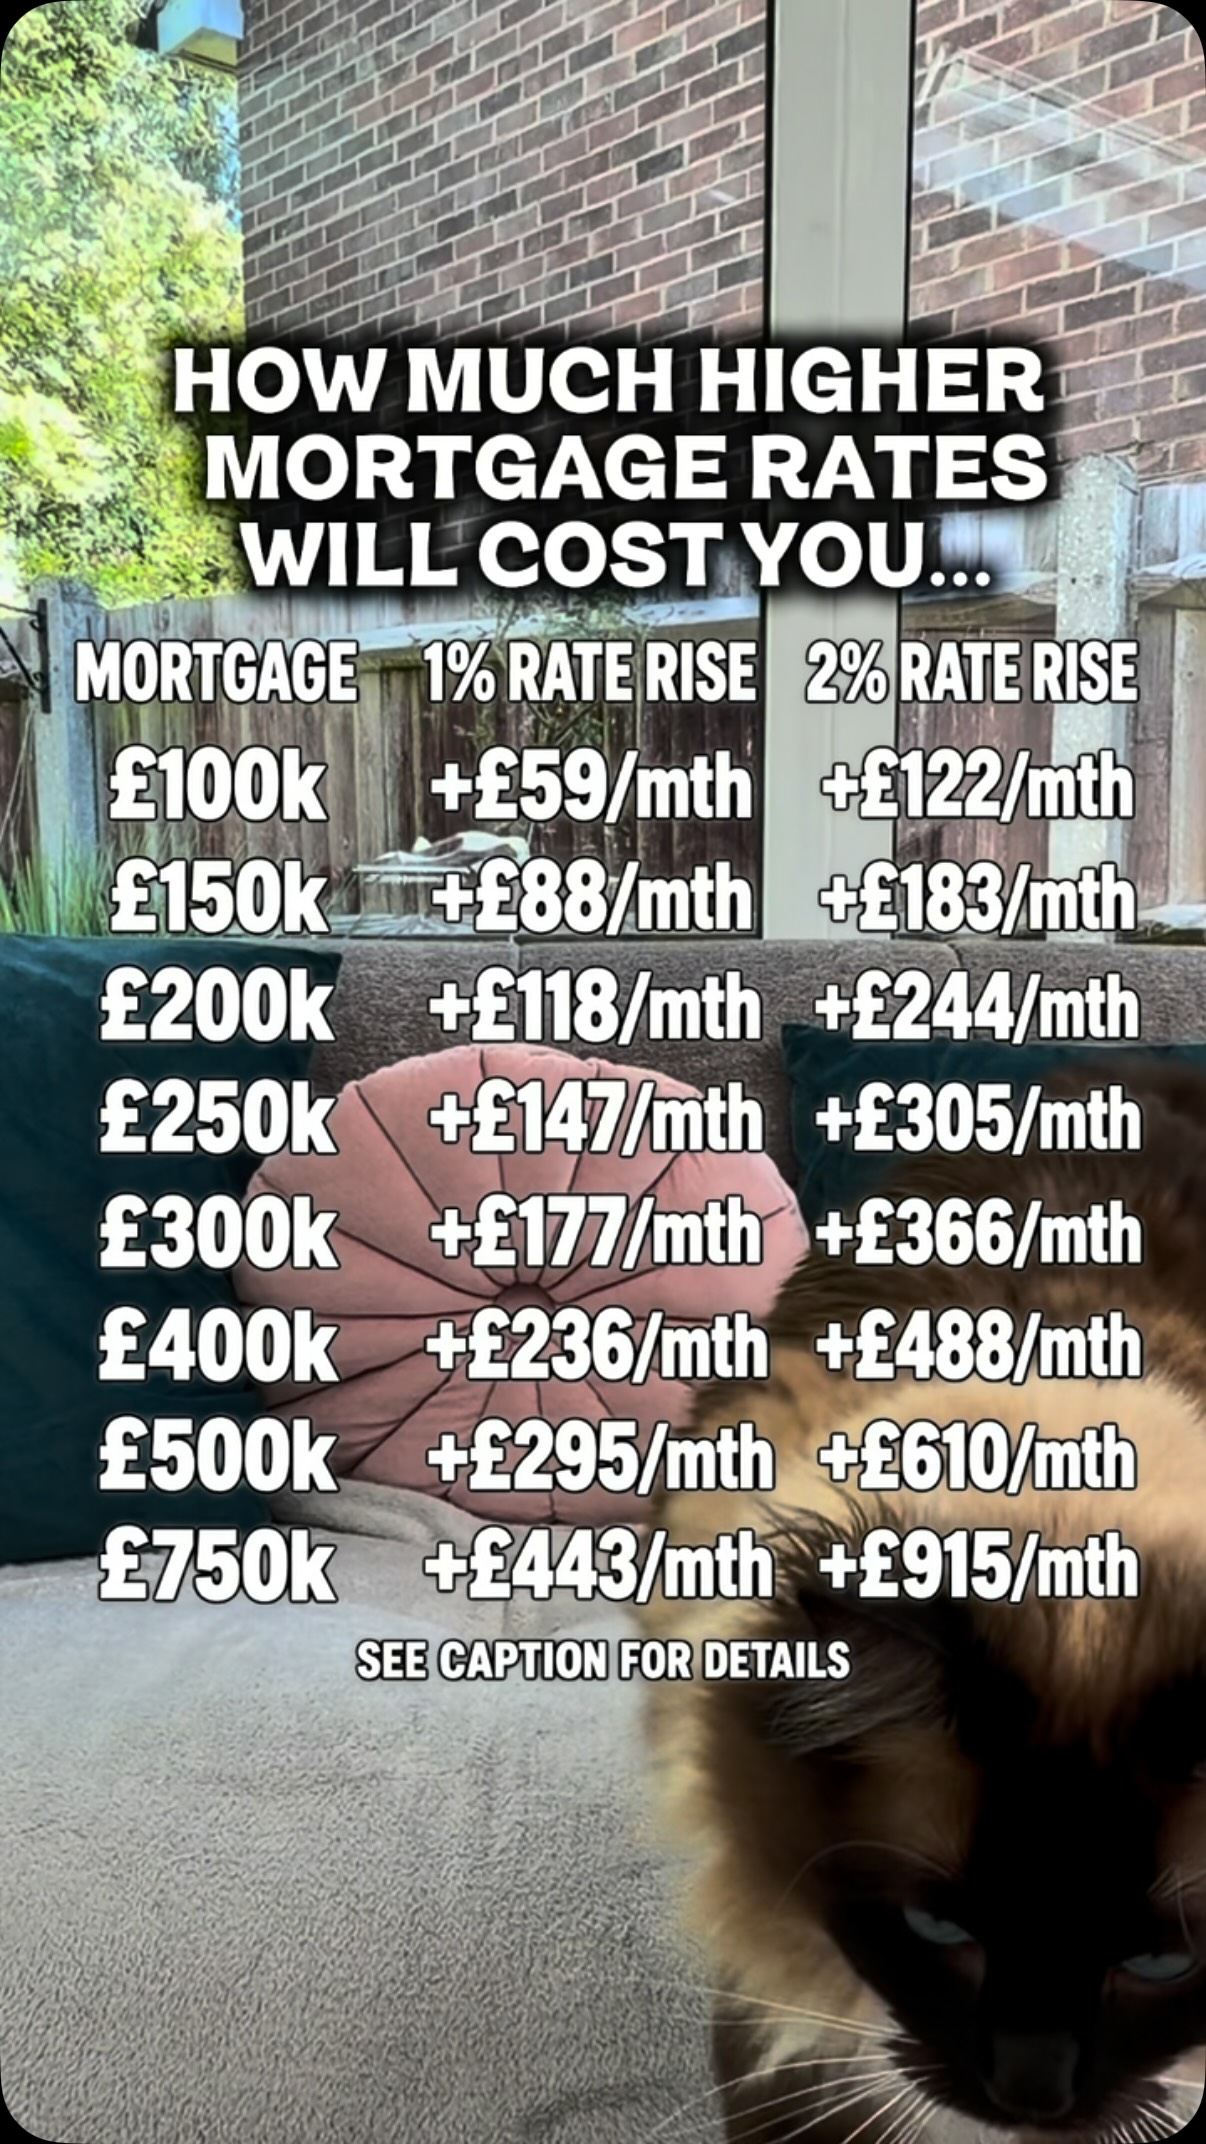
How much could your mortgage go up?
This table gives a rough idea of how much extra you might pay each month if your mortgage rate rises by 1 or 2 percentage points.
It can be useful if you are:
🏠 Coming off a fixed-rate deal and want a rough idea of what a higher remortgage rate could do to your monthly payment
or
📈 On a tracker mortgage and wondering how much your payment could rise if the Bank of England increases interest rates and your lender passes that on.
A useful rule of thumb from the table is:
For every £100,000 of mortgage, a 1 percentage point rise adds roughly £58 a month. A 2 percentage point rise adds roughly £119 a month.
So, for example:
* a £200,000 mortgage could rise by about £117 a month if your rate rose by 1%
* the same mortgage could rise by about £239 a month if your rate rose by 2%
Assumptions used in the table:
* repayment mortgage
* 25 years remaining
* 1% rise = 4.5% to 5.5%
* 2% rise = 4.5% to 6.5%
* figures rounded to the nearest pound
*
Your actual increase will depend on your current rate, new rate, mortgage balance and remaining term, so this is an illustration, not a quote.
And just to be clear, a 1% rate rise here means one percentage point — for example 4.5% to 5.5%, not 4.5% to 4.55%.
For a more personal calculation CLICK THE LINK IN BIO. to use my intrerest rates rise calculator
#mortgage #remortgage #interestrates #personalfinance #ukmoney
18
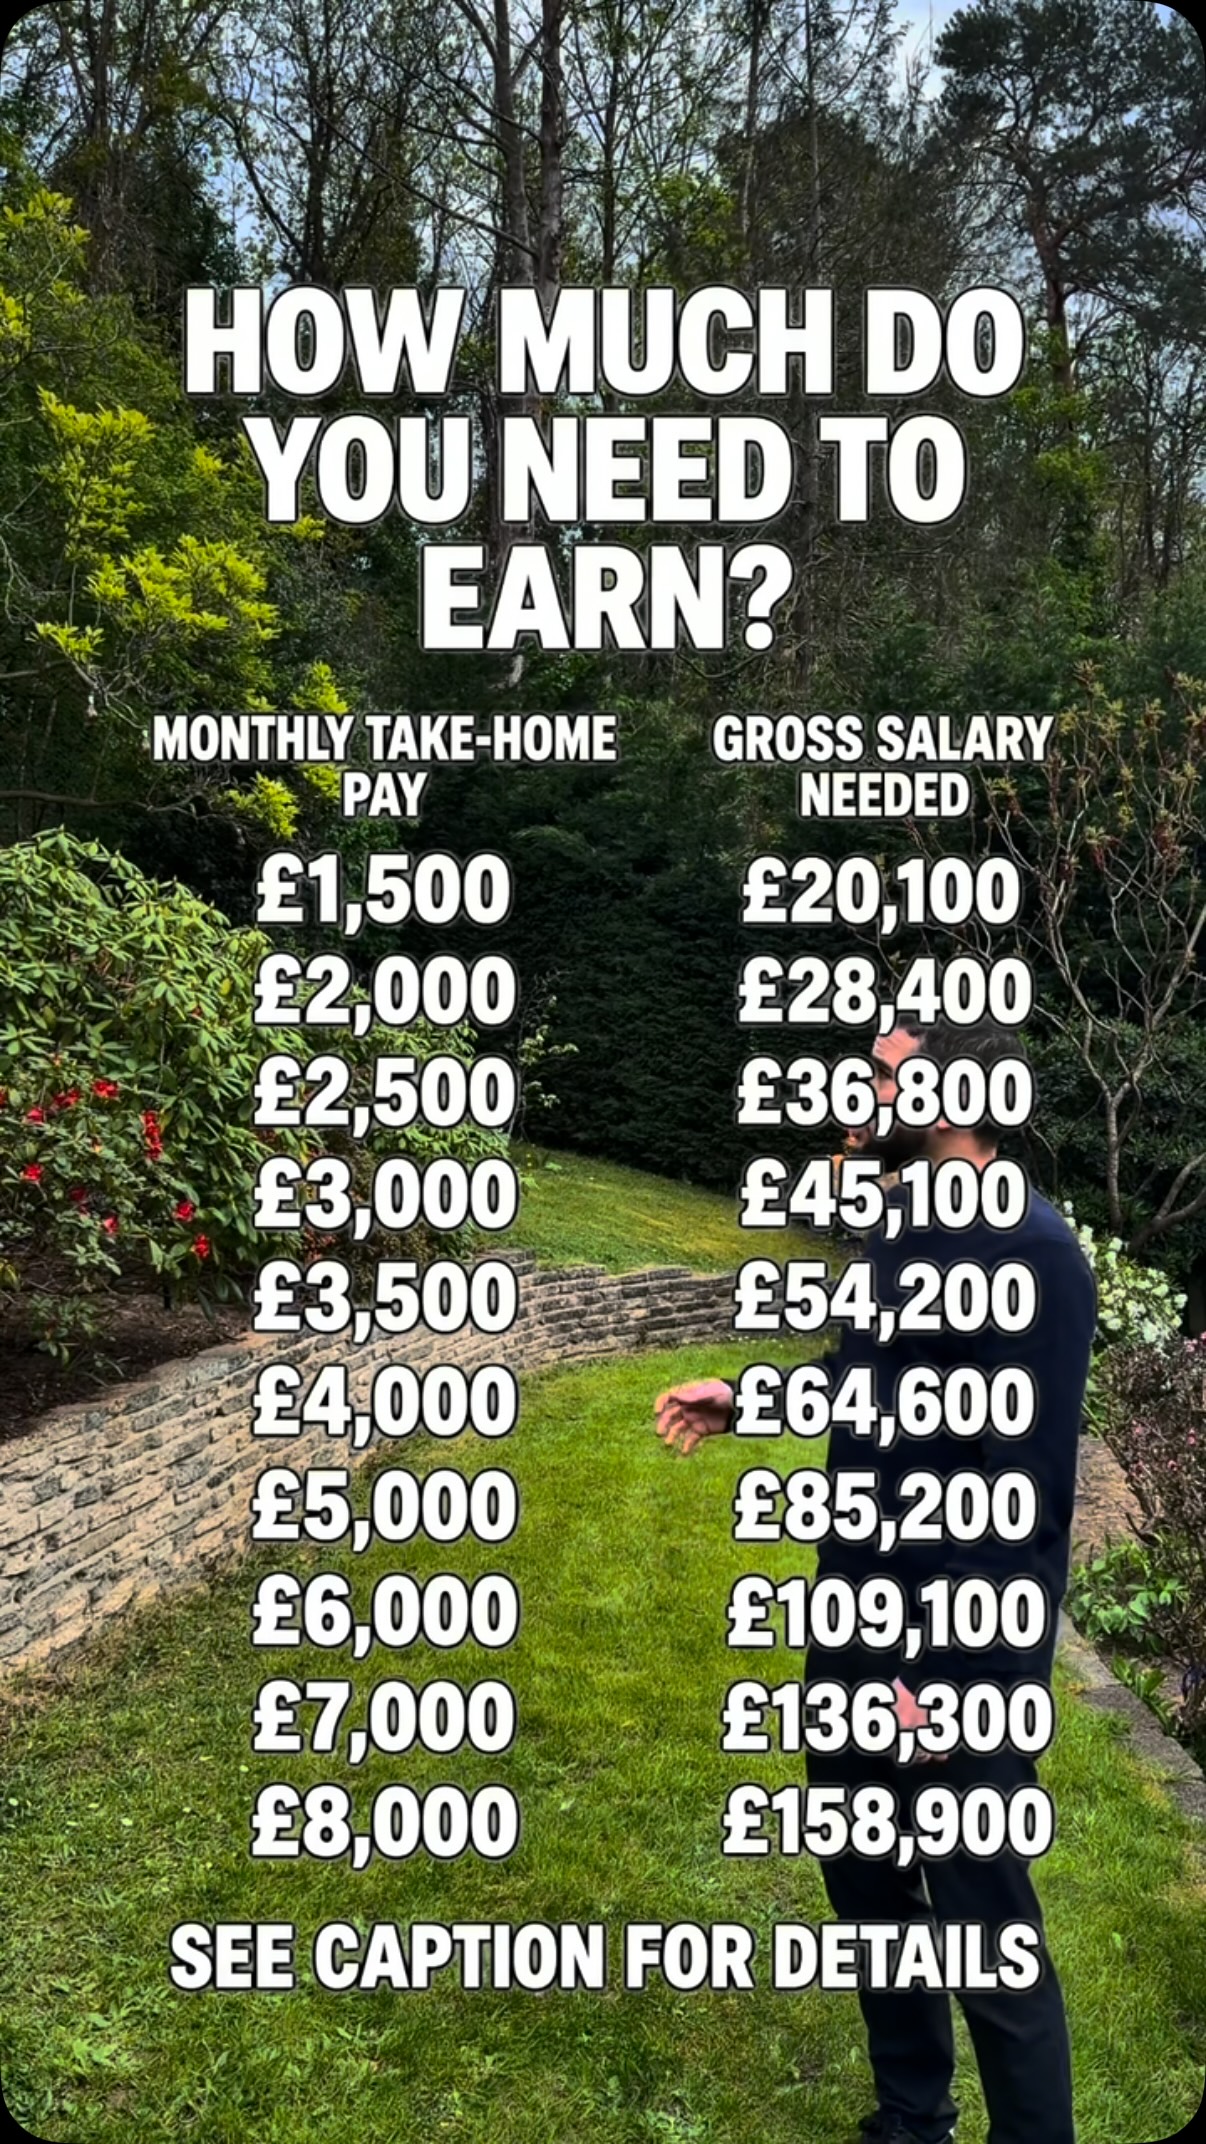
How much do you need to earn to take home a certain amount each month?
That’s what this table shows.
A few examples:
* £2,000 a month take-home needs a salary of roughly £28,400
* £3,000 a month take-home needs about £45,100
* £5,000 a month take-home needs about £85,200
It’s a useful reminder that your gross salary and what actually lands in your bank account can be very different.
Important assumptions:
These figures are only a guide and assume:
* you are employed
* paid through PAYE
* this is employment income, not income from investments
* you are on a standard tax code
* you pay standard employee National Insurance
* you are not making pension contributions
* you are not repaying a student loan
* you are not using salary sacrifice
* you are not receiving benefits in kind or other deductions
They are also based on England, Wales and Northern Ireland.
SEE PINNED COMMENT FOR FIGURES ASSUMING YOU PAY INTO YOUR EMPLOYER’S PENSION SCHEME VIA AUTO-ENROLMENT
If you live in Scotland, your take-home pay will differ because income tax bands are different.
Also if you are self-employed, have investment income, make pension contributions, repay a student loan or have other adjustments, your actual take-home pay may be different.
Save this so you can come back to it later.
#salary #money #personalfinance #ukmoney #moneytips
84