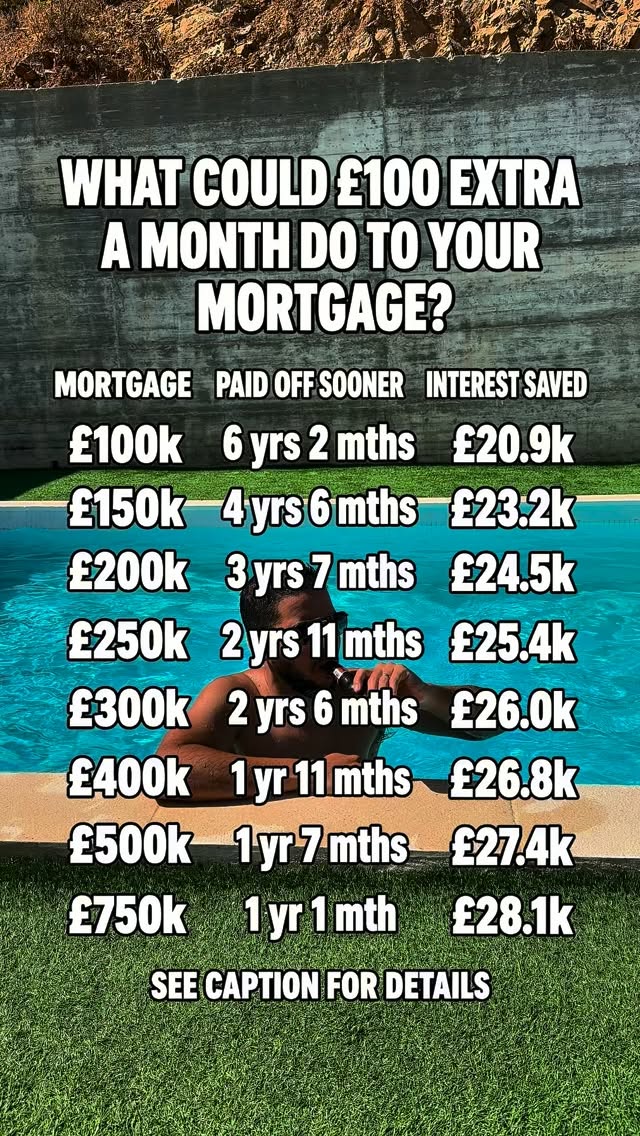
What could overpaying an extra £100 a month do to your mortgage?
Potentially, quite a lot.
This table shows how much sooner you could repay your mortgage, and roughly how much interest you could save, if you overpaid by £100 every month.
For example:
* £100k mortgage → paid off about 6 years 2 months sooner, saving around £20,900 in interest
* £200k mortgage → about 3 years 7 months sooner, saving around £24,500
* £500k mortgage → about 1 year 7 months sooner, saving around £27,400
The figures assume:
* a repayment mortgage
* 25 years remaining
* an interest rate of 5%
* the rate stays at 5% for the whole period
* you start overpaying immediately and continue every month
* no overpayment charges
Your actual saving will depend on your mortgage rate, remaining term and whether your lender limits penalty-free overpayments.
And remember, overpaying your mortgage is not automatically the best use of spare cash. Depending on your rate and circumstances, saving or investing could potentially give you a better return.
But if your priority is to clear your mortgage sooner and reduce the amount of interest you pay, even an extra £100 a month can make a meaningful difference.
For more info on overpaying your mortgage including the pros and cons click the LINK IN BIO
#mortgage #ukmoney #personalfinance #property #moneytips
24
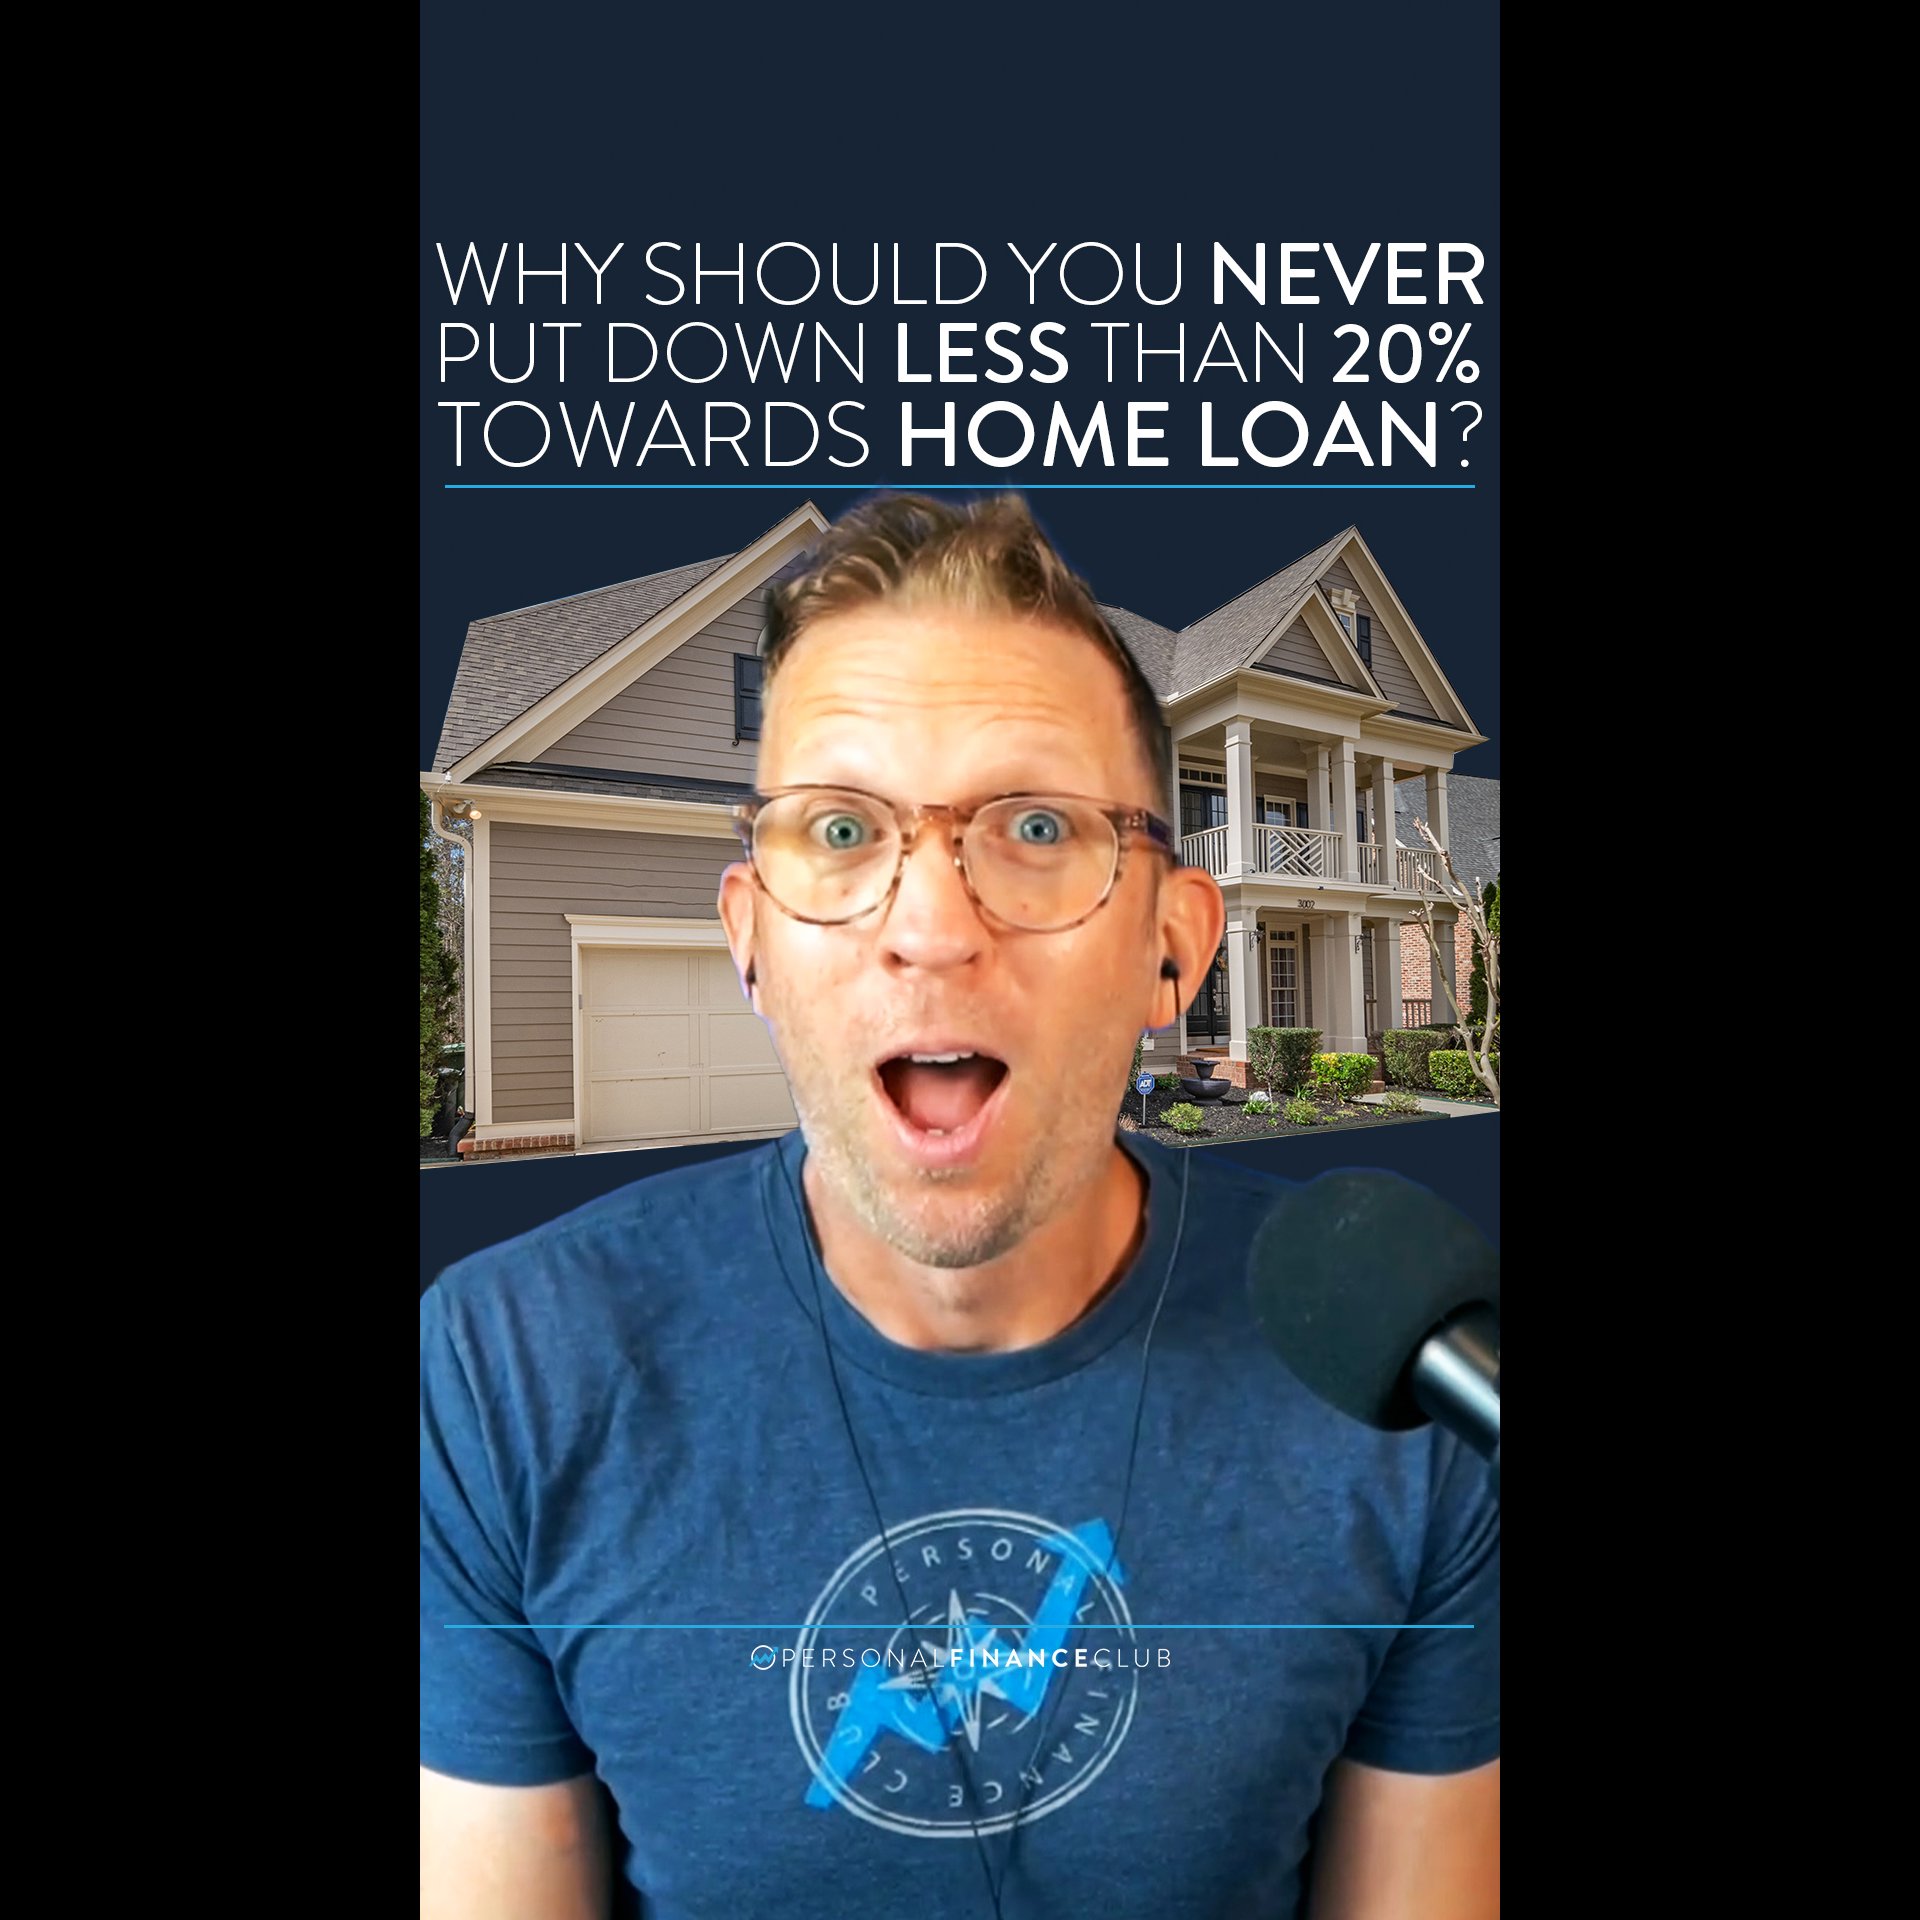
If you can’t get a 20% down payment together, then you should probably be renting. I know that’s not what people want to hear, but buying a house with the absolute minimum down payment just because the bank says you CAN is a pretty good way to end up house poor. Put down less than 20% and you’ll have a higher monthly payment because you’re borrowing more money. And then you get to add Private Mortgage Insurance (PMI) to the bill. FUN FACT: PMI is insurance for the bank, NOT you!
The bank is basically saying, “HMM…we’re a little nervous about how much money we just lent you. So we’d like YOU to pay for an insurance policy that protects US if YOU stop paying.”
So now you have less money saved, a larger mortgage, a higher monthly payment, and an additional insurance expense. You’ve put yourself in a position where the bank itself decided it needs extra protection from the risk of lending you the money.
Because being approved for a mortgage is not the same thing as being able to afford a mortgage. If you need to stretch to buy the house, drain your savings to get the down payment together, and then spend every month praying nothing breaks, maybe you don’t need a house yet.
Homeownership is not a requirement for adulthood. The goal is to build wealth, not win a race to see who can get a mortgage first.
As always, reminding you to build wealth by following the two PFC rules: 1.) Live below your means and 2.) Invest early and often.
-Jeremy & Jenn
#mortgage #personalfinance #downpayment #buyvsrent #livebelowyourmeans
660
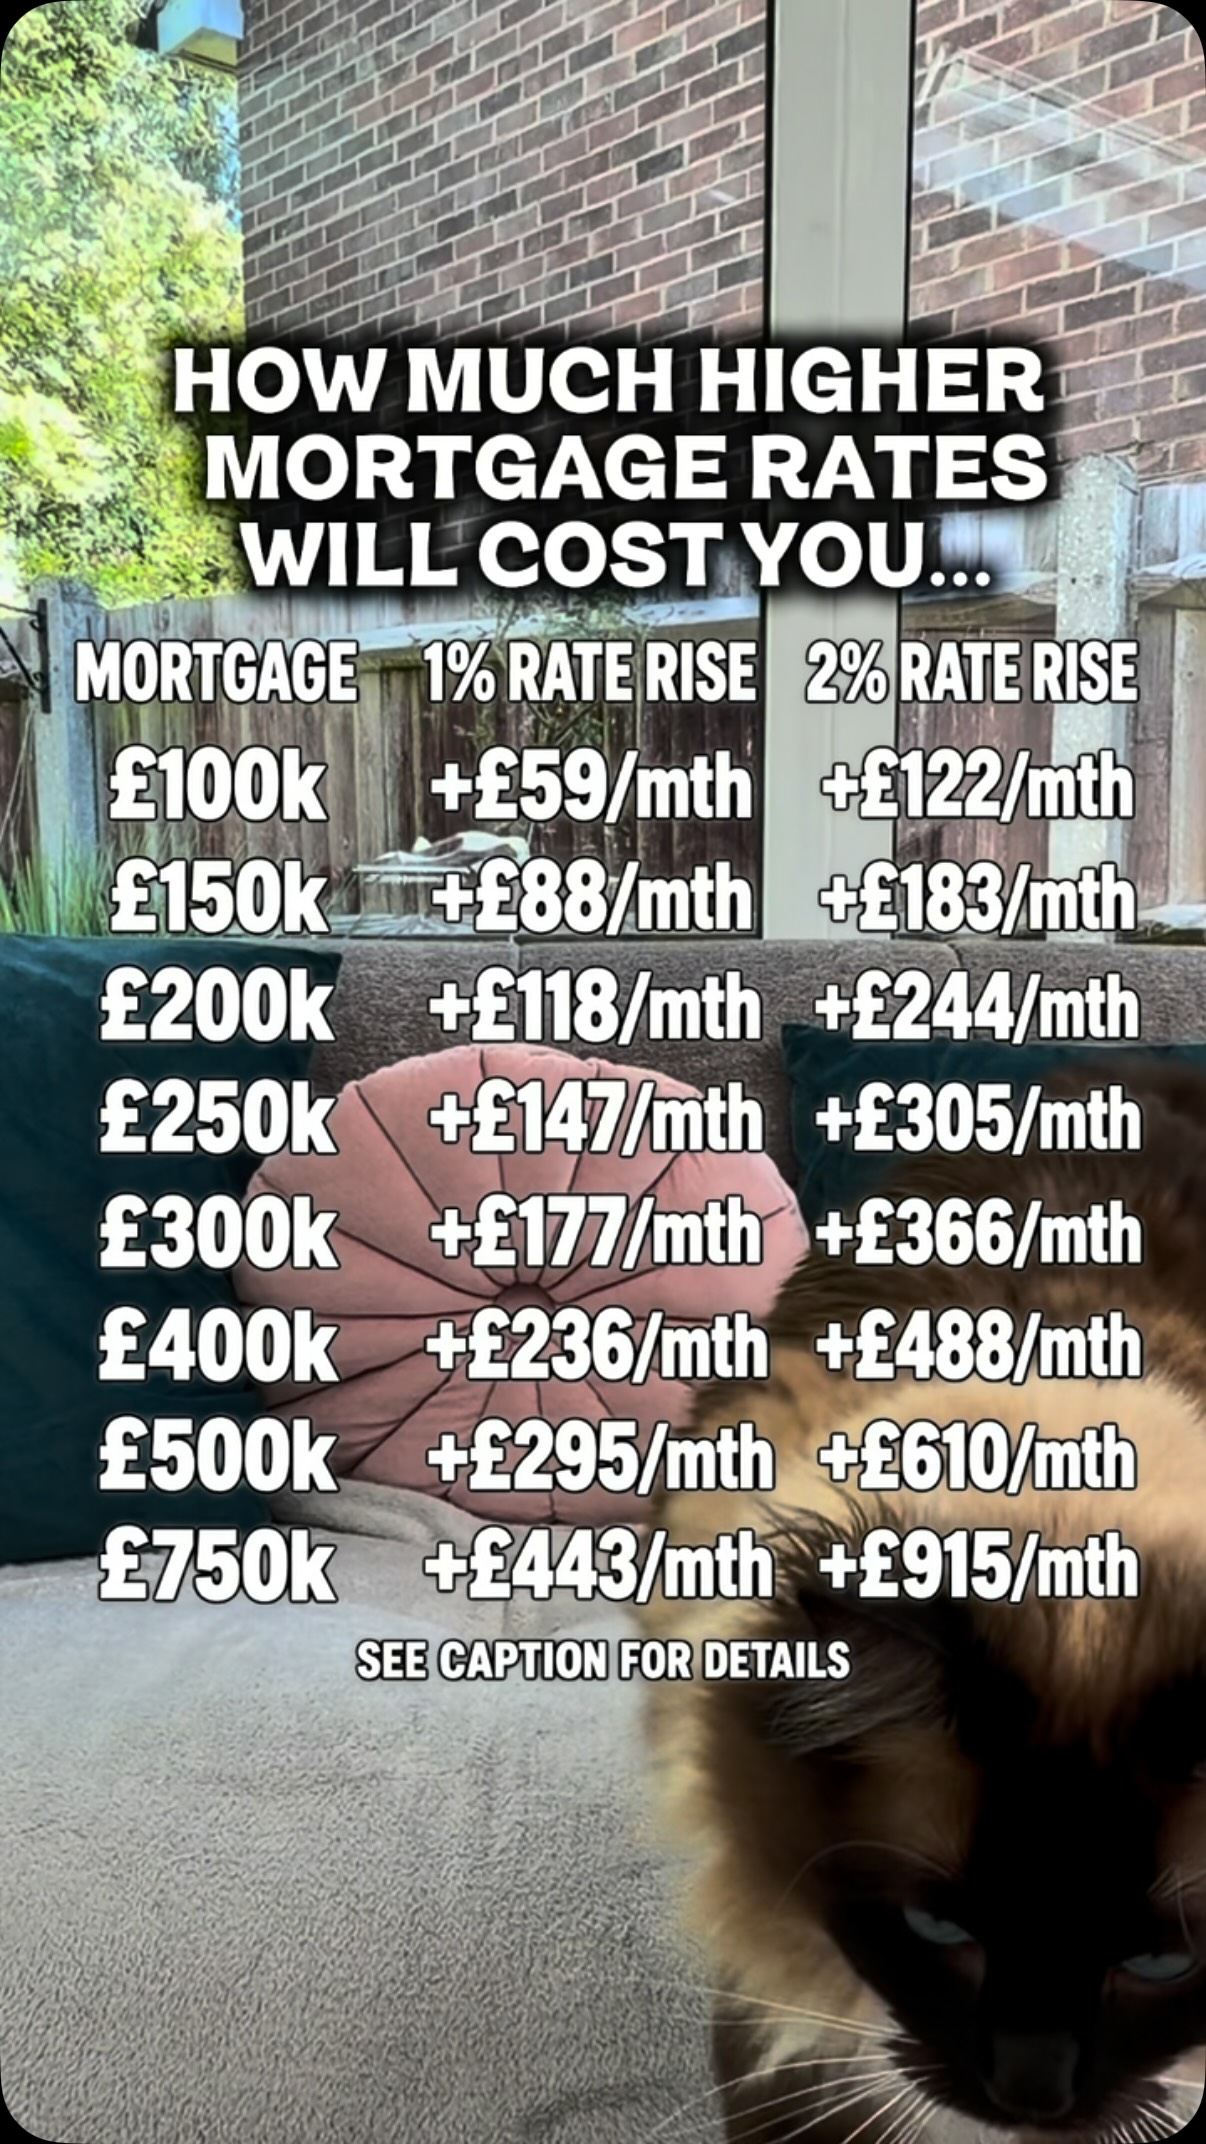
How much could your mortgage go up?
This table gives a rough idea of how much extra you might pay each month if your mortgage rate rises by 1 or 2 percentage points.
It can be useful if you are:
🏠 Coming off a fixed-rate deal and want a rough idea of what a higher remortgage rate could do to your monthly payment
or
📈 On a tracker mortgage and wondering how much your payment could rise if the Bank of England increases interest rates and your lender passes that on.
A useful rule of thumb from the table is:
For every £100,000 of mortgage, a 1 percentage point rise adds roughly £58 a month. A 2 percentage point rise adds roughly £119 a month.
So, for example:
* a £200,000 mortgage could rise by about £117 a month if your rate rose by 1%
* the same mortgage could rise by about £239 a month if your rate rose by 2%
Assumptions used in the table:
* repayment mortgage
* 25 years remaining
* 1% rise = 4.5% to 5.5%
* 2% rise = 4.5% to 6.5%
* figures rounded to the nearest pound
*
Your actual increase will depend on your current rate, new rate, mortgage balance and remaining term, so this is an illustration, not a quote.
And just to be clear, a 1% rate rise here means one percentage point — for example 4.5% to 5.5%, not 4.5% to 4.55%.
For a more personal calculation CLICK THE LINK IN BIO. to use my intrerest rates rise calculator
#mortgage #remortgage #interestrates #personalfinance #ukmoney
18
A new government scheme has arrived…
And you know I love a good breakdown 🔥
So here’s what you need to know:
The new scheme will give FTBs a new 20% equity loan on the property value - on a £300k property this would be £60,000.
And you would only need £7,500 as a deposit ✅
BUT…
No scheme is without a catch!
The loan will rise with the equity of the house, so if that property you buy increases to £400k, your outstanding loan also rises to £80k!
What do you think of this scheme?
#finance #education #personalfinance #mortgage
256
Mortgage deal ending in the next 6 months? Don’t wait for the renewal letter.
Lenders are pushing their fixed rates up. The good news is many will let you lock in a new deal up to 6 months before your current one ends. The new deal then starts when your current deal ends.
How to protect yourself:
1️⃣ Switching lender? You can usually lock in a new deal up to 6 months before your current one ends but will require a new affordability assessment
2️⃣ Staying with your lender? A product transfer can typically be secured up to 4 months early, depending on the lender - this won’t require an affordability assessment
3️⃣ If rates keep rising, you’re protected. If they fall, you can often swap to a cheaper deal before your old one ends (check for fees first)
4️⃣ Compare the total cost, fees included, not just the headline rate
5️⃣ Avoid taking out new credit before you apply
Save this if your deal ends in the next 6 months, and share it with someone who’s remortgaging soon.
This is an excerpt from episode 564 of my podcast. Listen to the full episode via the Link in bio.
This is general information, not personal financial advice. Make sure you speak to a mortgage broker about your own situation and all the mortgage options available. If you don’t have one you can trust then go to the link in bio where you will find the resources for this podcast episode including a guide on ‘How to find a mortgage broker you can trust’.
#mortgage #remortgage #mortgagerates #personalfinanceuk #moneytips
11