Most people measure financial security by their salary. Wrong number. 🙅♀️
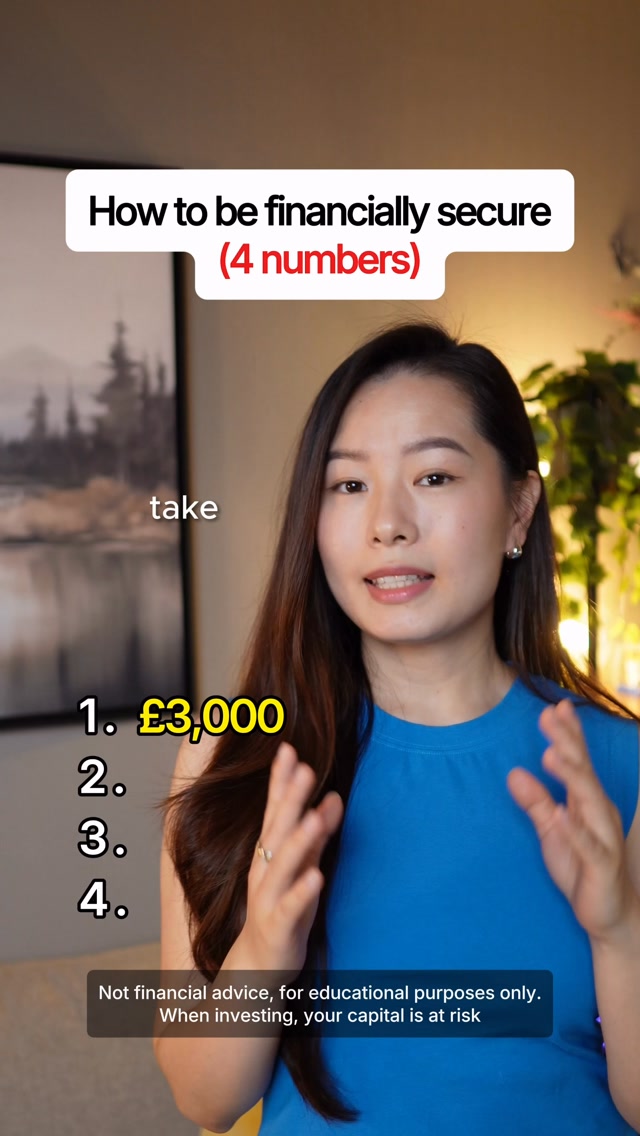
Security comes down to four:
1️⃣ Your emergency fund: 3 to 6 months of essential spending in easy-access cash. Your “life happens” money.
2️⃣ Your yearly investing number: the total you put to work each year across your pension and ISA. This decides how fast you get to number 4.
3️⃣ Your pension contribution: the % of your salary going in each month. At minimum, enough to get your full employer match. Skipping that is turning down free money.
4️⃣ Your FIRE number: roughly 25x your yearly spending (a rule of thumb, not a guarantee). The pot where work becomes optional.
You don’t need to hit all four tomorrow. You need to know them.
Save this and work out yours, and follow @michelle.huangyy for more financial education
⚠️ For educational purposes only, not financial advice. I’m not a regulated financial adviser, so do your own research or speak to one before making decisions. Capital at risk: investments can go down as well as up and you may get back less than you put in. Tax treatment depends on your individual circumstances and can change. Pension money usually can’t be accessed until age 55 (rising to 57 from 2028).
#personalfinanceuk #fire #emergencyfund #ukinvesting moneytips
149
You’ve reached the end 🎉